Hey there,
If you’ve ever found yourself Googling “are mobile gas stations insured?” at 2 a.m. while wrapping up a last-minute delivery for a construction site that ran out of fuel, you’re not alone. As the guy who runs our mobile gas station supply team—we’re the folks that bring fuel straight to job sites, fleet yards, or even events where pulling up to a permanent pump isn’t an option—I get this question all the time. Most of the time, people ask it because they’ve heard horror stories: a small construction crew using a beat-up old trailer to haul gas had a leak that ruined their equipment, or a pop-up event’s mobile tank got clipped by a forklift, and no one knew who’d cover the cost. Let me break this down like we’re chatting over a coffee (and no, I’m not just gonna give you a yes/no answer—this stuff’s way messier than that). Mobile Gas Station
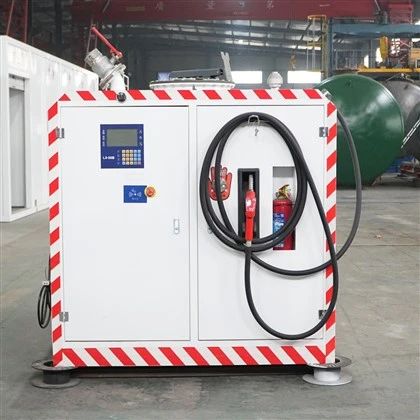
First, let’s get clear on what we’re even talking about here. A lot of people mix up mobile gas stations with those sketchy guys selling gas out of the back of a pickup on the side of the road (and for the record, we’ve got zero time for that garbage). The mobile units I supply—they’re basically DOT-approved trailers or skids, with double-walled tanks, built-in safety shut-offs, and we only haul fuel that’s been tested and tagged by local authorities. They’re not some random jerry can stuffed in a truck bed; they’re regulated, purpose-built mobile fueling systems. But even with that, insurance for these things isn’t like insuring your personal car. It’s way more nuanced.
When someone rents or buys a mobile unit from us, they usually assume we’re handing over a fully insured rig. Nope. Wait, hold up—hear me out. We have insurance on the unit itself, like the physical trailer, the tank, the pumps. But that only covers damage to the unit if something goes wrong with it. It doesn’t cover the stuff around it, or the fuel inside, or any third-party injuries. That’s where a lot of folks get burned. For example: last month, we rented a unit to a landscaping company that was refueling their midsize trucks at a city park. One of the crew tripped over the hose, spilled a small amount of gas, and a kid’s tennis shoe melted when it hit the puddle. The unit’s damage insurance didn’t cover the shoe, didn’t cover the park’s cleanup fee, didn’t cover the kid’s mom’s medical bill for a minor burn. That’s all on the renter, unless they have the right add-on.
So let’s split this into two big buckets: our insurance (the supplier’s) and your insurance (the person using the mobile station). That’s where most of the confusion lives. Our coverage as the supplier is usually two parts: general liability and physical damage. General liability covers things like if the trailer rolls into a fence while we’re delivering it, or if a pump malfunction spills gas on someone’s property during our control. Physical damage is for if the unit gets hit by a car, has a tree fall on it, or a fire starts in the tank (but only if it’s not our fault). The key here is “during our control”—once we drop it off and walk away, that insurance stops applying.
Now, what do you need? Because here’s the thing: if you’re a small construction crew just hauling a unit between job sites, you might think your regular general liability policy covers it. Let me stop you right there. Most standard business policies are written for permanent structures. They don’t cover mobile equipment that moves, especially stuff that handles flammables. Last year, a roofing company in Texas bought a unit from us and tried to use their existing business insurance when a wind gust knocked it into a power line, sparking a fire that took out their work truck and two neighboring homes. Their insurance denied the claim because the mobile fuel unit wasn’t listed as an insured asset on their policy. They ended up paying over $200k out of pocket. Ouch.
So what’s the fix? There are three main options for the people we work with, and we actually walk them through this step by step because we’ve seen the mistakes. First, add an endorsement to your existing general liability policy. This is like a rider that specifically covers mobile fueling equipment—both the unit itself and the fuel inside it, plus third-party damages. It’s not super expensive, usually a few hundred bucks a year, depending on how much fuel you’re hauling and how many sites you hit. Second, get a separate mobile equipment policy. If you’re using the unit every day for big operations (like a mining company that’s running 24/7), this is better. It’s more robust, covers things like theft of fuel, or if the unit gets stolen entirely, or even if your driver gets in an accident while moving it. Third, if you’re just using it for short-term events (like a music festival or a marathon), you can get a temporary insurance policy that kicks in for the duration of the event. We do this for a lot of the race organizers we work with—they only need it for a weekend, so it’s way cheaper than a yearly plan.
Wait, but what about the fuel itself? That’s another big question. A lot of people think “if I spill gas, my insurance covers it.” Nope. Fuel is a high-risk commodity, and standard policies don’t cover it. Even if you have an endorsement, you need to make sure it specifically names “hydrocarbon fuels” as a covered asset. I’ve had clients tell me their agent said “we cover all fuel” but then when we reviewed the policy, it only covered diesel, not gasoline. That’s a last-minute headache waiting to happen. We actually provide a quick 10-point check list to every customer when they take a unit—one of the points is “confirm fuel coverage is listed on your policy”—because we want them to get it right, not because we’re trying to sell them extra stuff.
Now, let’s talk about edge cases because that’s where people get tripped up. What if you’re renting a mobile unit from someone else, not buying it? A lot of rental companies will try to pawn off their insurance on you, but don’t assume that. Last quarter, a food truck festival used a mobile unit from a rental company that said “we’re fully insured.” But when a food truck backed into the unit, puncturing the tank and spilling 50 gallons of gas into a storm drain, the rental company’s insurance only covered the unit’s repairs, not the environmental cleanup (which in that city is like $15k, because storm drains lead to rivers). The festival ended up on the hook for that because their own liability policy didn’t cover third-party mobile equipment damage. Moral of the story: when you rent, always get a certificate of insurance from the rental company, and then have your own agent review it. Don’t just take their word for it.
Another edge case: personal use. Wait, can you use a mobile gas station for personal stuff? I’d advise against it, but if you do, forget it—regular personal auto insurance doesn’t cover mobile fuel units. Even if it’s a tiny 500-gallon skid for your farm, you need a commercial policy. We had a guy in Ohio try to buy a unit from us with his personal car insurance, and his agent laughed and said “you can’t insure a flammable storage tank on your personal plan.” So save yourself the hassle and don’t even try that.
What about our responsibility as the supplier? We take this stuff seriously, not just because we don’t want to get sued, but because our clients’ livelihoods depend on their fuel being available without them worrying about insurance nightmares. That’s why every unit we supply is inspected monthly by a third-party safety firm—no cutting corners on that. We also include a free 30-day insurance consultation with a partner broker when someone buys or rents a unit from us. We’re not insurance agents, so we can’t give legal advice, but we know who to call to get you the right policy. That’s the stuff no one tells you when you Google “are mobile gas stations insured”—it’s not just about the unit, it’s about how you use it, what’s inside it, and who’s on the hook when something goes wrong.
Let me wrap this up with a real example, because stories stick. A construction client of ours in Florida, they work on road projects all over the state. A couple years back, they ignored our advice and didn’t add the fuel endorsement to their policy. Their unit got hit by a tornado (yes, tornadoes in Florida—who knew?) and the tank split, spilling 200 gallons of gas into a wetland. The state’s environmental agency hit them with a $75k fine. Their insurance denied it, their general liability didn’t cover fuel spills, and they had to take out a line of credit to pay it. Now, they’re one of our repeat customers, and they go out of their way to tell every new client “do not skip the insurance check.” Last month, another construction crew with us had a minor spill (like, 5 gallons) on a job site in Georgia. They had the right policy, it covered the cleanup, no fine, no stress. That’s the difference between doing it right and doing it wrong.
So to answer the original question: yes, mobile gas stations can be insured, but not all insurance is equal. The unit itself is covered by the supplier, but you need your own coverage for the fuel, third-party damages, and any incidents that happen after the unit’s delivered. Don’t rely on the supplier’s insurance, don’t assume your regular policy covers it, and always get a second opinion from your agent before you sign anything.
If you’re a contractor, event planner, farm owner, or anyone who’s looking to use a mobile gas station for your operations and want to make sure you’re covered—hit us up to chat through your specific needs. We’ve worked with everything from small local landscaping companies to big mining outfits, and we can point you in the right direction for insurance that actually fits your use case. No sales pitch, no pressure, just real talk about staying safe and staying covered.
Mobile Explosion-proof Fuel Station References: National Fire Protection Association (NFPA 30A), Commercial Insurance for Mobile Fueling Assets, Occupational Safety and Health Administration (OSHA) Guideline for Flammable Liquid Storage, State Environmental Protection Agency (EPA) Mobile Fuel Spill Response Requirements.
Shandong Jingcai Industry and Trade Co., Ltd.
As one of the most professional mobile gas station manufacturers and suppliers in China, we also support customized service. With abundant experience, we warmly welcome you to wholesale high quality mobile gas station in stock here from our factory. Contact us for free sample.
Address: Caojiazhuang Village Industrial Park, Lingcheng Town, Qufu City, Jining City, Shandong Province.
E-mail: shandongjingcai888@gmail.com
WebSite: https://www.sdjingcaicn.com/
